01
Clarity.
Understand what your plan could do.
02
Confidence.
Compare the benefit with the cost.
03
Coordinated Execution.
Bring your advisor, TPA and CPA together.
FICTIONAL CASE STUDY · BLUE-COLLAR BUSINESS
A SIMPLE plan. A growing HVAC company. A reason to review.
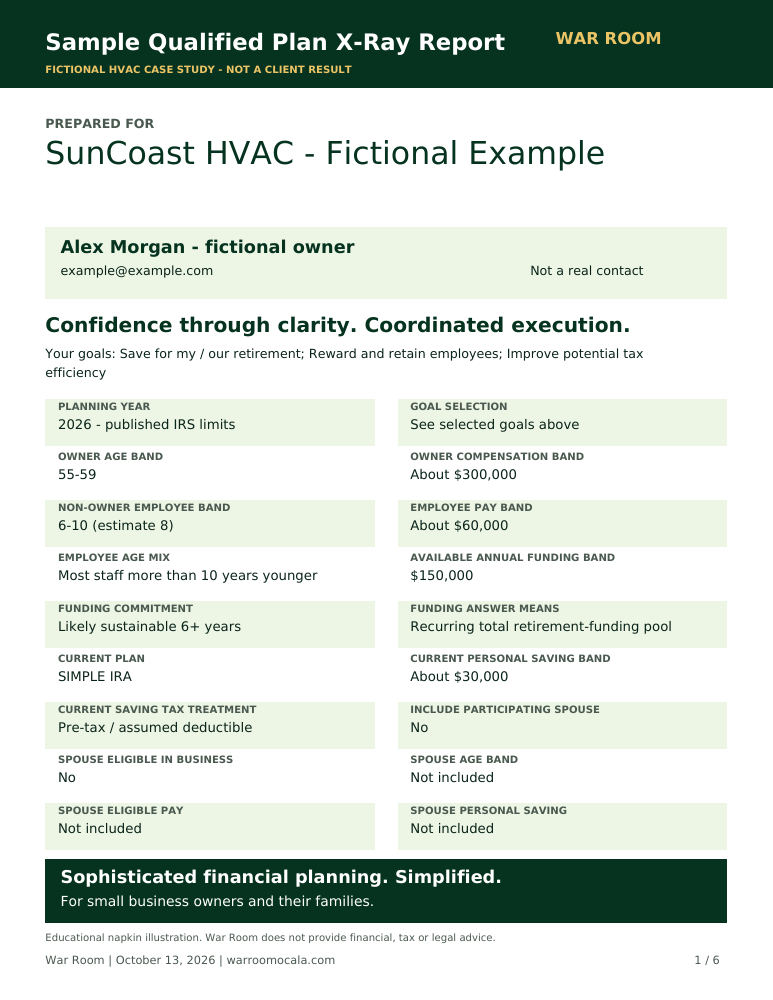
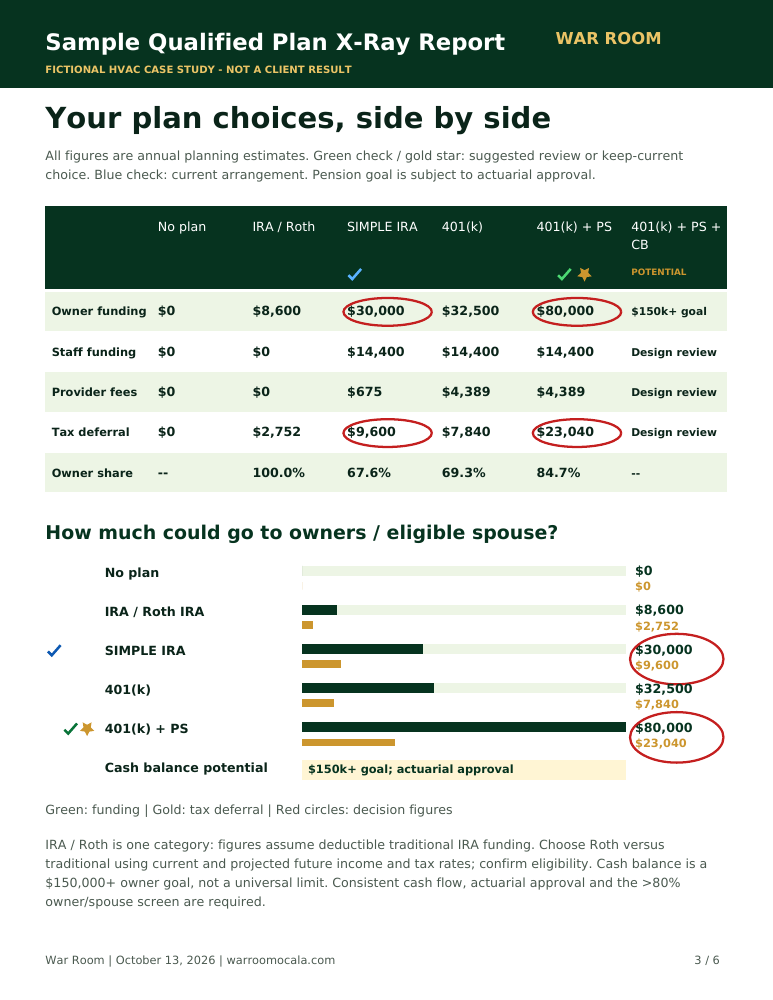
SunCoast HVAC illustrates an owner, age 57, with eight employees, $150,000 in sustainable annual funding capacity, and a SIMPLE IRA. A 401(k) with profit sharing could create more contribution room—if a TPA census review confirms the design.
These dollars could support retirement goals for the owner, family and employees rather than current income tax. Tax deferral is not permanent tax elimination. The modeled owner share is 84.7% of retirement contributions, subject to compliant census-based allocation review.
More than tax savings: invest in the people who build your business.
A thoughtfully designed plan could support employees’ futures, reward tenure through suitable vesting and contributions, and help reduce turnover costs. The goal is to maximize the compliant allocation to owners and eligible family members while delivering meaningful employee benefits. Your advisor and TPA should confirm eligibility, vesting, testing and allocations; pension designs also need actuarial review.
These potential culture and retention benefits are additional considerations—not guaranteed results or amounts included in the economic benefit calculation.
Why a quick check can be useful
In Capital Group’s April 2025 survey of 1,000 small business owners, 36% cited perceived cost as an obstacle to offering a retirement plan. This is a cost-perception statistic—not the percentage of owners who have outgrown a plan. There is no national outgrown-plan percentage asserted here.
Capital Group research and survey contextLet the numbers decide. A better design could help. Your current plan could also be the right fit.
WAR ROOM · QUALIS QUICK SCREEN
Could your plan do more for you?
Start with eight quick choices. Open more detail only when you need it.
Before you begin: You can calculate, view and save a report without submitting contact details. Please use approximate ranges and a business label; do not enter SSNs, account numbers or employee census information. Contact submission is disabled here. Nothing is sent or booked. Website hosting and technical-data practices are covered by the Privacy Policy.
1 · Your business profile
Having any of these goals supports investigating a plan. It does not automatically justify an expensive design.
W-2 wages or eligible self-employment earnings, not distributions or total business profit.
Exclude owners and the participating spouse added below. Include other likely eligible staff; related companies and highly compensated employees need separate review.
A rough average among those likely eligible, not companywide payroll.
Total recurring retirement-funding pool, before deciding what goes to owners, employees or provider fees. Include owner salary dollars you would redirect into retirement; do not count those dollars twice. Preserve operating reserves, debt payments and tax reserves.
STEP 2 · ALMOST DONE
Almost done. Let’s compare your plan.
Add your current plan and owner contribution. Optional assumptions let you refine the illustration.
Required to prepare your company’s report.
2026 · Published IRS contribution limitsUse ages, compensation and cash flow expected in the selected year. 2027 official limits are pending; provisional figures must be refreshed before funding.
Choose a plan to see its age-adjusted 2026 contribution ceiling. Amounts above that ceiling will be unavailable.
We will count the spouse separately from non-owner employees. Confirm eligibility and compensation with the plan administrator.
For an IRA-only comparison, eligible joint compensation may support a spousal IRA. Employer-plan contributions require the spouse’s own eligible compensation and plan eligibility.
Special SIMPLE limits and employer elections must be confirmed by the administrator. Employer funding is added to employee deferrals; do not compare a total contribution against the deferral-only limit.
Self-employed earnings must be adjusted for the deductible part of self-employment tax. The maximum effective contribution rate is generally 20%, rather than 25% of W-2 compensation.
The two-person IRA comparison assumes sufficient joint eligible compensation. Business-plan figures include a spouse only when business eligibility and compensation are indicated; final eligibility must be confirmed.
Each spouse has a separate IRA limit and catch-up eligibility.
Enter a percentage, not a decimal. 28.5 means 28.5%.
Illustrative accumulation horizon, not a life-expectancy projection.
Used only to compare incremental staff funding, not to certify a new plan.
QUALIS™WAR ROOM | QUALIS MASTER TEMPLATE v1.1
STEP 3 · YOUR RESULTS
Your retirement plan Napkin Math review
WHAT THIS MEANS FOR YOU
The goal: find a worthwhile opportunity—or give you confidence to stay with what works.
401(k) / profit-sharing screening economics
The detailed ranges below compare your current arrangement with the 401(k) / profit-sharing screen. They do not estimate the unapproved cash balance maximum.
Annual owner funding difference—Funding gap: what a possible design could allow you to save above your current annual contribution. Not tax savings.
Owner deposit difference over 10 years—Annual extra savings repeated for 10 years, before investment growth. Assumes continued affordability and eligibility.
10-year modeled after-tax advantage*—
15-year retirement income difference*—
Your potential opportunity, shown as a range
One low-to-high range reflects different employee-benefit costs. It is an illustration to decide whether a professional review could be worthwhile—not a promised outcome.
Business budget that could warrant a closer look—Company cash-flow estimate after selected employee and owner employer 401(k) funding, plus assumed administration. Not an allowable cash balance contribution.
What you told us
What could change each year
Gross funding reference (before taxes)
Bars show gross funding or expenses in different categories. The net funding proxy is not an after-tax increase in wealth, and unknown costs suppress the proxy.
Year-one funding / tax spread (not profit)Not calculatedAdditional owner funding + illustrative tax effect − incremental staff costs − estimated fees. This combines restricted retirement funding and cash effects; it is not spendable income or net new wealth.
RECOMMENDED next action:
Hypothetical illustration: additional pre-tax funding, selected tax assumptions, incremental staff costs and fees. Ten-year net value compares after-tax plan assets with an equivalent-cash outside investment. The retirement model draws that difference down over 15 years. Advanced contributions require independent actuarial confirmation. Unknown costs suppress net estimates; no guarantees.
You can view and save this educational report without providing contact details. Do not enter SSNs or employee census data. Contact submission is disabled here. Nothing is sent or booked. A certified plan-design professional, third-party administrator (TPA), enrolled actuary and tax advisor must validate actual eligibility, nondiscrimination testing, age-weighted funding, deduction limits and commitment levels before adoption.
1. Quick opportunity check
STEP 1 OF 3The first four selections determine whether the detailed questions open automatically. The Roth question never disqualifies a business.
War Room • QUALIS / Module 1
Can your cash flow support a better retirement plan?
An owner earning $250,000–$500,000+ may have outgrown a SIMPLE, SEP, or traditional 401(k). This optional screen tests company affordability, the estimated safe harbor employee funding floor, and whether an independent cash balance feasibility study could be worth commissioning. It does not calculate an actuary-approved pension limit.
Use total owner business income for this screen, not just qualified-plan compensation. Distributions are not automatically plan compensation.
Available every year after working-capital needs, tax reserves, debt service and payroll. Exclude employee salary deferrals.
Actual gateway, nondiscrimination and combined-plan costs may be higher; 0% is not a representation that testing passes.
Only a planning allowance, not an actual quote; excludes initial setup or additional employee pension benefits.
CPA must assess deductibility, entity economics, tax brackets and timing. Tax impact is not cash flow.
Complete the annual income and budget fields to screen for an opportunity.
Important: A cash balance plan is a defined-benefit pension. Contribution requirements, retirement benefit limits, staff accruals, plan funding rules and combined 401(k)/pension deductions require a third-party administrator, enrolled actuary and CPA. The remainder shown here is at most uncommitted budget capacity, not a permissible owner pension contribution or tax deduction.
QUALIS
Preliminary retirement-plan opportunity illustration · 2026
Could an upgrade improve the owner's financial outcome?
WAR ROOM / QUALIS • OWNER CASH-FLOW FIT
Additional pension-design screen
3% nonelective safe harbor employee floor (illustrative)
Additional staff profit sharing (scenario)
Owner employer 401(k) / profit-sharing funding (estimate)
Upper-bound budget remaining before cash balance staff accruals
Annual change in combined owner retirement funding
—
Proposed less current
Owner share of change in staff + plan fees, after tax
—
Assumes 37% marginal federal rate
Projected incremental after-tax wealth
—
Versus investing equivalent cash outside the plan
Annual plan comparison
| Current owner contributions | |
|---|---|
| Illustrative new owner contributions | |
| Of proposed contributions: assumed Roth catch-ups | |
| Current staff contributions | |
| Illustrative new staff contributions | |
| Change in annual company fees | |
| Change in annual business staff + fee costs | |
| Owner share of those costs after assumed federal income tax |
Projected long-term comparison
| Added owner's retirement funds, after withdrawal tax | |
|---|---|
| Less: alternative after-tax investment of incremental cash required | |
| Modeled difference in after-tax wealth |
A negative alternative cash amount means the upgrade frees cash rather than consuming it.
Roth availability
Possible first-plan tax credits — verification required
An eligible first-time employer may qualify for startup-cost credits for up to three tax years and, in some cases, employer-contribution credits. Eligibility depends on employee composition, headcount, costs and whether substantially the same workers were covered by a prior employer plan during the preceding three tax years. Credits are not added to the modeled benefit because this questionnaire cannot validate eligibility.
A potential planning opportunity deserves professional verification
Could an independent review improve your retirement outcome?Your results could indicate an opportunity to improve your projected after-tax retirement wealth. Before making changes, consider scheduling a third-party independent review with a financial advisor experienced in serving business owners, preferably a Certified Exit Planning Advisor (CEPA®) trained in business transition and exit planning. A qualified retirement-plan administrator or designer and your tax professional should also verify plan provisions, employee costs, contribution allocations and actual tax impact.
This directory is maintained by the Exit Planning Institute. QUALIS is not affiliated with, or endorsing, any individual advisor. CEPA is an exit-planning credential, not a substitute for specialist retirement-plan or tax advice.
Next step:
Educational-use disclaimer. This is a preliminary, hypothetical illustration—not individualized tax, legal, investment, retirement-plan design, or fiduciary advice. Results depend on approximate band values, assumed 37% current and future federal marginal tax rates, investment growth, investment-gain taxation and business ownership. A lower future income-tax rate can materially change the outcome. Employee eligibility, vesting, benefit testing, employer contribution limits, plan documents, fees, payroll taxes, business deductions, qualified business income, state taxes, credits, current-plan provisions and future laws may change actual results. Before changing a plan, obtain a third-party review from a qualified retirement-plan administrator/designer and the owner's tax and financial professionals.